If you live in the Hamilton or Cincinnati, Ohio area and recently received a letter from your insurance agency saying that one of its insurance company relationships is ending, you may be wondering what happens to your insurance now.
Maybe the letter says your policies will be moved — or “rolled” — to another insurance company. That usually creates more questions than it answers:
- Do I have to move to the new insurance company?
- Can I stay with my current insurance carrier?
- Can another independent agency take over my existing policy?
- Should I let my current agency move me to another company?
- Should I get new quotes before deciding?
- If the new carrier matches my current rate, will that price last?
These questions matter because of a distinction consumers do not always realize: your insurance company and your insurance agency are not the same thing.
If an independent agency loses its contract or appointment with an insurance company, that does not necessarily mean the insurance company is leaving the Hamilton or Cincinnati market. And it does not necessarily mean you have only one option.
What does it mean when an insurance agency loses a carrier?
Independent insurance agencies typically represent multiple insurance companies.
The insurance company issues the policy and assumes the risk. The independent agency sells and services the policy and represents that company under an agency agreement.
Sometimes that relationship ends. An insurance company may terminate an agency’s appointment, or the agency and carrier may end the relationship for other reasons.
When that happens, something has to be decided about customers who currently hold policies with that company. What that looks like depends on the carrier, the agency agreement, and the circumstances of the termination.
One possible outcome is what the industry calls a book roll or book transfer.
What is an insurance book roll?
An agency’s “book of business” is its collection of customer policies.
If the agency can no longer write or service policies with a particular insurance company, it may move eligible customers to another company it represents. Rather than handling each customer individually, the agency may arrange to transition a larger group of customers at once.
For the agency, that provides continuity. For the customer, it can make the transition simpler.
But there is still a question worth asking: is moving to that replacement company my only option, or simply one of them?
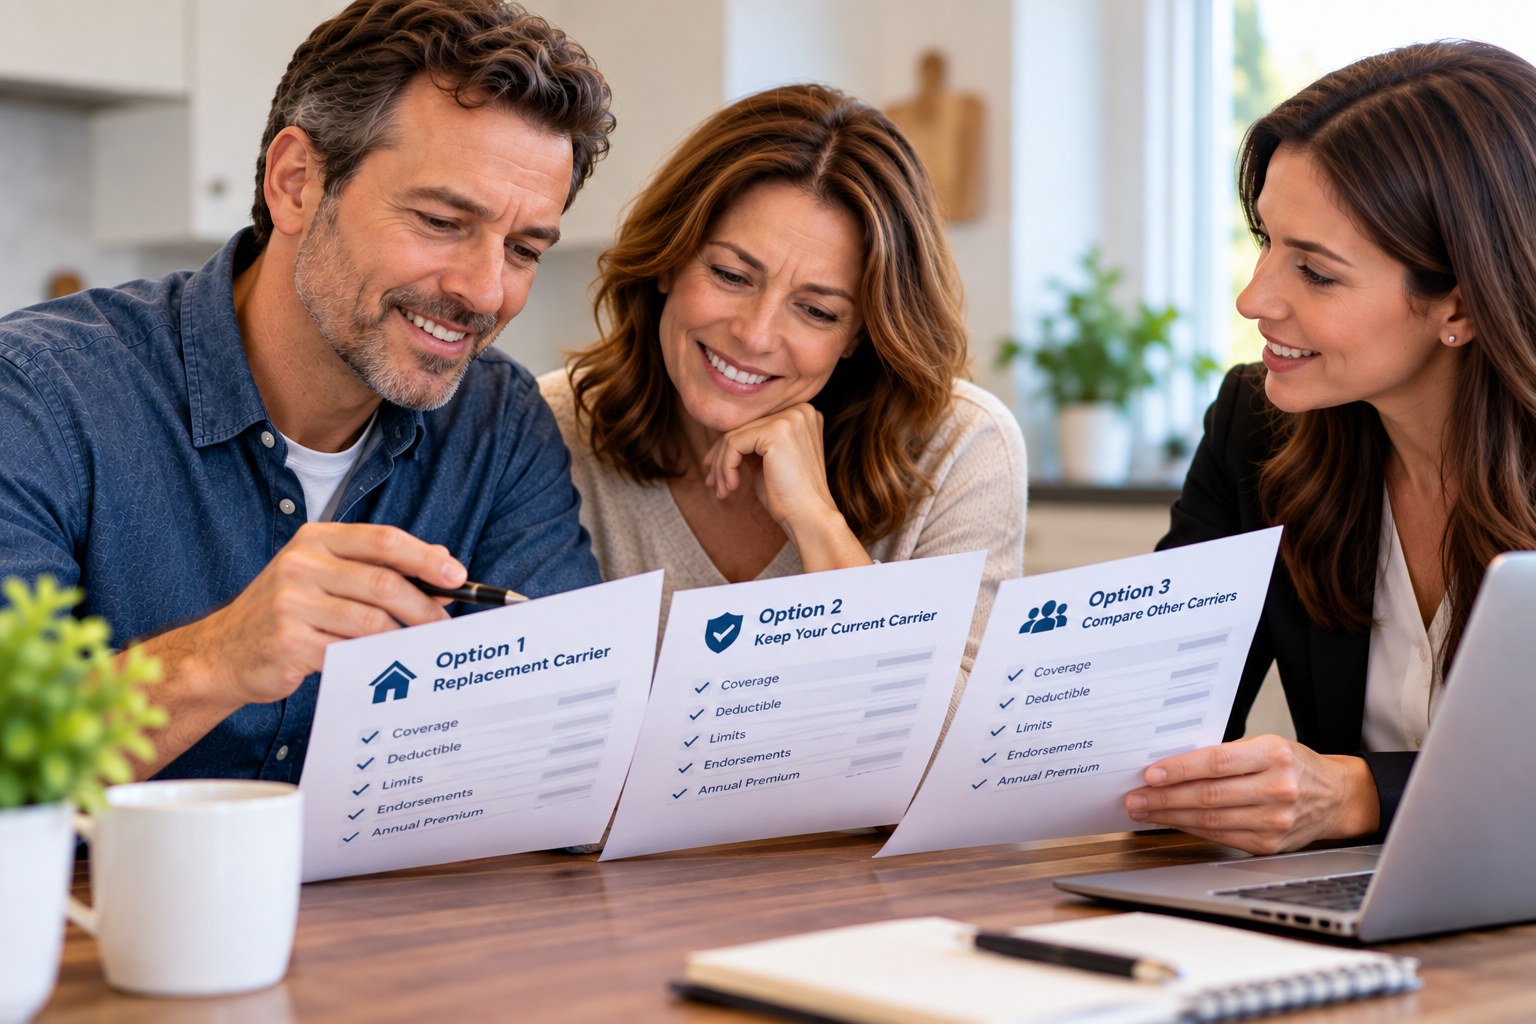
Option 1: Move to the insurance company your current agency recommends
There are real advantages to this.
You already know your agent. Your agent knows your insurance history. And if the agency has found another company offering similar coverage at a competitive price, the transition may be straightforward.
For many customers, this is a perfectly good outcome.
But you should still understand what you are being offered. Ask your agent:
- Is my coverage changing?
- Are my deductibles changing?
- Are there endorsements or benefits on my current policy that the new company does not include?
- How does the new premium compare with what I pay today?
- Is this the replacement carrier’s normal pricing for me, or is there special pricing, a discount, or a transition program tied to moving this book of business?
That last question matters more than it might seem, because the initial price is only part of the story.
If the new company matches my current price, will that price last?
This deserves an honest answer: nobody can promise what your premium will be several renewals from now.
When a group of customers moves from one insurance company to another, the replacement company may use pricing, discounts, or transition strategies designed to make its initial offer competitive. That can make the first-year number attractive.
But an initial premium is not a guarantee of future premiums. Rates can rise, fall, or stay relatively stable, and they are affected by the company’s filed rates, claims experience, inflation and rebuilding costs, changes to your property or vehicles, driving history, coverage selections, discounts, and other underwriting factors.
So if you are offered a price close to what you pay today, that is worth considering. But it is also worth asking a different question: how does that offer compare with what other insurance companies would charge me right now?
A matched price and a competitive market price are not the same thing.
Option 2: Find out whether you can keep your existing insurance company
This is the option consumers most often do not realize they have.
An agency losing a carrier appointment does not mean the carrier has become unavailable everywhere. Because independent agencies each hold their own appointments, a company that one agency can no longer access may still be available through a different agency that remains appointed with it.
There are generally two ways that can work.
Path one: an agent-of-record change
An agent-of-record change is a carrier-approved process that transfers servicing of an existing policy from one appointed agency to another without changing the insurance company. The policy stays in place; the agency handling it changes.
When it is available, this is usually the cleaner path, because the existing policy continues uninterrupted.
But not every insurance company allows it.
Many carriers permit agent-of-record changes. Some do not allow them at all. Others allow them only under specific conditions, which can include:
- A signed request from the policyholder, often on the carrier’s own form
- Waiting periods before the change takes effect
- Restrictions on making the change close to a renewal date
- Rules governing how and whether agencies may solicit these changes
- Limits on how often a policy can move between agencies
Any agency you speak with should know that particular carrier’s rules. If they are not sure, that is worth noticing.
Path two: rewriting the policy with the same company
If the carrier does not permit an agent-of-record change, an agency that holds an appointment with that company may still be able to write a new policy with the same insurance company.
You would keep the insurance company, but you would have a new policy rather than a continuation of your existing one.
That distinction has practical consequences worth understanding before you choose it:
- The policy gets a new number and a new effective date
- Underwriting is generally reviewed again, which can affect eligibility or price
- Discounts tied to how long you have held the existing policy may or may not carry over
- Your current policy has to be cancelled, so ask how any return premium is calculated
- Coverage should be rebuilt deliberately and compared line by line, rather than assumed to transfer
So if you would rather stay with your current insurance company, there may be two ways to do it. Ask which one that carrier actually permits in your situation, and what the practical differences would be for your policy.
Option 3: Compare the market before you decide
If your insurance is already being disrupted, that may be the most useful moment to look at the whole market rather than only the replacement being offered.
Maybe staying with your existing company is best. Maybe the replacement your current agency recommends is a strong offer. Maybe a different company provides a better combination of coverage and price.
The point is that the option described in the letter does not have to be your only option — and asking for quotes does not commit you to anything.
Shopping is not the same thing as switching. It simply gives you the information to make a better decision.
When comparing, look at more than premium. Compare:
- Home and auto coverage limits
- Deductibles
- Home replacement cost
- Roof coverage and how roof losses are settled
- Water backup and other endorsements
- Liability limits
- Uninsured and underinsured motorist coverage
- Discounts
- Optional coverages
- The overall annual premium
Then put the choices side by side: keep your current carrier, move to the proposed replacement, or choose another company entirely.
Do not compare price without comparing coverage
Suppose your current policy costs $2,000 and the replacement company offers $2,010. That looks like a near-perfect match.
But what if the deductible changed? What if roof coverage moved from replacement cost to actual cash value? What if water backup coverage disappeared? What if the liability limits are not identical?
Or suppose another company comes in at $1,700 but significantly reduces important coverage. The lowest number does not automatically represent the best value.
Try to make the comparison as close to apples-to-apples as possible, and look at both halves of the question: what am I paying, and what am I getting?
Questions to ask before your policy is moved
If you have received a letter saying your agency is losing a carrier and your policy may be moved, ask:
- Do I have to move to this particular insurance company?
- Can I remain with my existing insurance company through a different appointed agency?
- Does my carrier allow an agent-of-record change in my situation?
- If not, can the policy be rewritten with the same company?
- Will my coverage change when I am moved?
- Are my deductibles changing?
- Is the replacement premium based on special transition pricing or discounts?
- If there are special discounts, how long do they apply?
- Can I see a side-by-side comparison of my current and proposed policies?
- Can I get quotes from other insurance companies before deciding?
Those questions turn something that feels like it is happening to you into a decision you are actively part of.
What if the replacement quote is better?
Then that matters, and you should weigh it.
A genuinely good option is worth taking seriously regardless of who is offering it. If the replacement carrier provides the coverage you need at a price that makes sense, that belongs in your decision.
The goal here is not to talk you out of anything. It is to make sure you know the choices actually available to you before the decision is made for you.
In summary: your agency may be changing carriers, but you still have choices
If you are in Hamilton, Cincinnati, or the surrounding communities and you have received a letter saying your insurance is being moved, the most important thing to understand is that the decision may not already be made for you.
Depending on your situation, you may have three paths:
- Move to the replacement carrier your current agency recommends.
- Find out whether you can keep your current insurance company — either through an agent-of-record change or by rewriting with that same company through another appointed agency.
- Compare the market and weigh your options before deciding.
There is no single answer that is right for everyone, and which paths are actually open to you depends on the carrier, your policy, and the timing. But before your insurance is moved, it is worth finding out which ones apply.
While this situation is currently affecting policyholders in the Hamilton and Cincinnati area, the same general options apply anywhere in Ohio when an agency loses a carrier appointment.
Frequently asked questions
What happens to my policy if my insurance agency loses its contract with my carrier?
An agency losing an appointment does not by itself cancel your policy mid-term. What happens next depends on the carrier, the agency agreement, and the circumstances. In some cases the agency may arrange to move eligible customers to another insurance company it represents — a transition sometimes referred to as a book roll. In others, the carrier may reassign servicing, or the affected policies may be non-renewed at expiration. In most situations you still have time to ask questions, request comparisons, and consider your options before anything changes.
Is my insurance company leaving Ohio if my agency loses the contract?
Not necessarily. An agency losing an appointment is a change in the relationship between that agency and that carrier. The insurance company may still be writing business in your area through other appointed agencies.
Do I have to accept the replacement carrier my agency recommends?
Not necessarily. Depending on the carrier, your policy, and the timing of the transition, you may have other options. Those could include moving to another appointed agency, rewriting with the same carrier when that is available, or shopping other insurance companies. Ask what applies to your specific situation before a decision is made for you.
What is an agent-of-record change?
It is a carrier-approved process that transfers servicing of an existing policy from one appointed agency to another without changing the insurance company. The existing policy continues; only the agency handling it changes.
Do all insurance companies allow agent-of-record changes?
No. Many carriers permit them, but some do not allow them at all, and others allow them only under specific conditions — such as a signed request on the carrier’s own form, waiting periods, restrictions near a renewal date, or rules about how agencies may solicit them. The rules vary by company.
What if my insurance company does not allow an agent-of-record change?
An agency appointed with that company may still be able to write a new policy with the same insurance company. You would keep the carrier but receive a new policy rather than a continuation of the existing one, which generally means a new policy number and effective date, a fresh underwriting review, and the need to compare coverage carefully. Your current policy would also need to be cancelled.
Will I lose discounts if my policy is rewritten with the same company?
Possibly. Discounts tied to how long you have held a specific policy may not always carry over to a new one. Ask before the policy is rewritten so there are no surprises at the first renewal.
If the replacement carrier matches my current price, is that price locked in?
No. An initial premium is not a guarantee of future premiums. Rates can change based on the company’s filed rates, claims experience, rebuilding costs, changes to your property or vehicles, coverage selections, and other underwriting factors.
Does getting quotes mean I have to switch?
No. Shopping is not the same as switching. Requesting a comparison gives you information; you are free to stay where you are.
What should I compare besides price?
Coverage limits, deductibles, home replacement cost, how roof losses are settled, water backup and other endorsements, liability limits, uninsured and underinsured motorist coverage, discounts, and optional coverages. A near-identical premium can sit on top of meaningfully different coverage.
How long do I have to decide?
That depends on your renewal date and the timeline in the letter you received. Because some options are affected by timing — including whether an agent-of-record change is permitted close to renewal — it is generally better to ask questions early rather than close to the deadline.
Talk to us before you decide
If you have received one of these letters, the most useful first step is usually a straightforward comparison.
Start a quote or contact our team and we will walk through what you are being offered and compare it against the options available to you.
You may also want to review our homeowners insurance and auto insurance pages, or browse our personal insurance FAQ.
The decision should be yours, and it should be an informed one.
Lighthouse Agency Insurance
Licensed in Ohio, Indiana, Kentucky, and Tennessee | Serving Fairfield, Hamilton, West Chester, Butler County, and Greater Cincinnati
This blog provides general educational information and does not constitute insurance advice or legal counsel. Your insurance coverage is determined by your policy document. For questions about your specific coverage or claims, contact your insurance agent or company directly.